AI-Based Valuation of Loans with Termination Rights under § 489 BGB
Photo by Marcellin Steinhaus on Unsplash (downloaded on 30.10.2026)
From Challenge to Innovative Solution
Thousands of VaR scenarios, one neural network and a convincing approach: Finbridge provided specialist support to NRW.BANK in developing an AI-based valuation method for loan termination rights under § 489 BGB.
The result: a significant acceleration of the valuation with comparable accuracy to the established reference model. The valuation process is fully automated, and the business and technical implementation has been successfully completed. The following case study shows how this was achieved and why the approach is also suitable for other products.
Significantly faster valuations with comparable accuracy to the reference model.
Case Study: AI-Based Valuation of Termination Rights in Loans under § 489 BGB: An Application at NRW.BANK
Loans governed by § 489 BGB include a statutory prepayment option, allowing borrowers to repay a fixed-rate loan generally ten years after full receipt of the loan, subject to six months’ notice [1]. From a financial mathematics perspective, this results in an embedded optional component structurally analogous to an American option. A risk-appropriate valuation therefore requires specialised procedures that closely follow the methodology used to price traditional American options.
NRW.BANK initially developed a modern AI-based approach for the valuation of linearly amortising loans (see Fig. 1) within the Monte Carlo simulation framework of the Value-at-Risk (VaR) market risk calculation. Using an established option-pricing model as a benchmark, a neural network was trained. This provides a useful complement to classical models by ensuring high scalability while maintaining transparent model logic – especially when processing thousands of VaR scenarios. Classical models are still used as benchmarks and also serve as the primary model for areas such as profit-and-loss accounting.

While classical models require considerable computing time for a very large number of Monte Carlo scenarios, the AI approach allows a massive acceleration – with comparable accuracy to the benchmark model. The valuation process developed is fully automated, with weekly updates of real portfolio subsets and benchmark validation using the reference model. This solution represents a major advancement for NRW.BANK in the context of modern, model-driven risk control. After the successful business and technical implementation of the AI valuation system, a formal alignment of the governance framework with relevant audit bodies will take place before the final integration into VaR calculations.
AI-based valuation methods enable the efficient processing of thousands of VaR scenarios and complement classical valuation models.
Background: Why American Options Are Complex to Value
American options give the holder the right, but not the obligation, to exercise the option at any time before expiry. European options, by contrast, can only be exercised at maturity. This difference in exercise timing determines the valuation methodology: European options can be valued analytically, e.g. using the Black-Scholes model. American options can only be valued numerically, for example using the Cox-Ross-Rubinstein binomial method or Monte Carlo methods.
Traditional lattice and PDE methods are precise but slow. For stress tests and VaR calculations with thousands of scenarios, this often leads to compromises: the use of simplified approximation methods, the neglect of non-linear effects or the omission of a full repricing.
This is where Deep Pricing comes in. A neural network learns the relationship between the market parameters and the benchmark prices of a reference model. It then replaces the time-consuming numerical calculation for certain scenarios with immediate predictions.
The benchmark price of the reference model serves as the training label for the neural network.
The following overview positions Deep Pricing among the established valuation methods:
| Method | Idea | Strength | Weakness |
|---|---|---|---|
| Binomial/trinomial tree (e.g. Cox-Ross-Rubinstein) | Discrete time/price lattice, backward induction | Simple, provides hedging deltas | Slow with fine lattices |
| Hull-White interest rate lattice | Models interest rate processes with mean reversion | Suitable for callable bonds and swaptions | Smile only via recalibration |
| Finite differences (PDE) | Discretised valuation equation with early exercise | Very precise | Somewhat more complex set-up |
| Longstaff-Schwartz Monte Carlo | Regression of continuation values on simulation paths | Flexible for many risk factors | Requires many paths |
| Deep Pricing (DNN) | Network learns the mapping from parameters to prices | Significantly reduced valuation times after training | Requires reference prices as labels |
Table 1: Comparison of valuation methods for American options (Source: Finbridge)
Outlook: Promising Results for American Options
The valuation of termination rights is only the beginning. Finbridge has also investigated the Deep Pricing approach for classical American options. The results are promising: the neural network delivers prices that are almost identical to those of the reference model, in a fraction of the computing time. This allows for further applications wherever large numbers of valuations need to be performed quickly.
Initial results for American options show almost identical prices in a fraction of the computing time.
Deep Pricing with Finbridge
We support you at every step: from creating the training data and developing and validating the AI model through to integration into your existing calculation processes.
Would you like to know whether Deep Pricing could add value for your institution? Get in touch with us.
References
Authors
Your Contact
MORE ABOUT AI

Finbridge is your partner for ML services in finance & banking. Using Machine Learning (ML), we drive innovation, increase efficiency, and improve the customer experience. Our AI solutions support areas such as customer service, risk management, process automation and data analytics. We offer modular ML solutions from our extensive ML toolbox and adapt them flexibly to your needs, whether through customised consulting projects or efficient software packages. Discover business cases for successful use cases.

pbb Deutsche Pfandbriefbank AG, a leading specialist bank for real estate and public investment finance, collaborated with Finbridge, a consulting firm specializing in financial services, to modernize the hidden reserves/losses (HRL) process. By employing automation and machine learning, the partnership aimed to improve data analysis and make the process more efficient.

The wider acceptance and active development of machine learning techniques and data analytics have made it possible to optimize and automate business processes. This presents a lucrative opportunity for banks to redesign their operations to cut processing times and improve transparency. We present the potential of these techniques by applying a machine learning approach to a hidden reserves/losses process that can often be found in the finance departments of banks.
Machine LearningFinancial Engineering
Further Trends
Thousands of VaR scenarios, one neural network: discover how Finbridge supported NRW.BANK in developing an AI-based approach to valuing loan termination rights under § 489 BGB. Deep Pricing accelerates valuation while maintaining comparable accuracy to the reference model.

The Minimum Bail-in Data Template replaces the previous Bail-in Data Set.
Initial submissions are required this year as part of dry runs. Our insight highlights current developments and solution approaches.
The Minimum Bail-in Data Template replaces the previous Bail-in Data Set.
Initial submissions are required this year as part of dry runs. Our insight highlights current developments and solution approaches.
Find out more about PHACCT, our high-performance solution for portfolio fair value hedge accounting, developed with pbb Deutsche Pfandbriefbank The modern web application fully maps the hedge process, offers full transparency and seamless integration into existing IT landscapes PHACCT enables faster processes, lower costs and flexible data access for future-proof banking solutions.

The EU is actively working on creating a digital supplement to existing cash - the digital euro (D€). The introduction of such a means of payment would probably bring about a major change in all payment transactions, from everyday shopping in the supermarket to the offers of a commercial bank, which is why it is definitely advisable to take a closer look at this concept. We have summarized the reasons for creating such a means of payment, what exactly is currently planned and what the technical and legal basis for it should look like.

Finbridge conducted a Benchmarking Study in the field of Resolution Planning. This posting gives an overview of the study’s essential findings and an outlook for 2024.
Finbridge is your partner for ML services in finance & banking. Using Machine Learning (ML), we drive innovation, increase efficiency, and improve the customer experience. Our AI solutions support areas such as customer service, risk management, process automation and data analytics. We offer modular ML solutions from our extensive ML toolbox and adapt them flexibly to your needs, whether through customised consulting projects or efficient software packages. Discover business cases for successful use cases.
In December 2019, the European regulatory authorities introduced the IFR and the IFD as a new prudential framework for investment firms. The present insight discusses some of the IFD/IFR mandates subsequently issued by the EBA und gives an overview of present and upcoming requirements.
pbb Deutsche Pfandbriefbank AG, a leading specialist bank for real estate and public investment finance, collaborated with Finbridge, a consulting firm specializing in financial services, to modernize the hidden reserves/losses (HRL) process. By employing automation and machine learning, the partnership aimed to improve data analysis and make the process more efficient.

Both the ECB and the EBA are currently working in parallel on the topic of an integrated reporting system. This shall allow financial institutions to provide comparable, uniform and redundancy-free data. In this article, we give an overview of current delevopments and explain the application using concrete examples.
Liquidity in Resolution is one of the seven dimensions of the EfB and one of the current working priorities of the SRB. Apart from further literature about liquidity by the FSB and the ECB, the SRB has published three publications about liquidity in resolution on its website. We analyse the content of these publications and give an overview of existing and upcoming requirements.

Insurers must address fundamental strategic issues. It is more important than ever to anticipate emerging trends and prepare for change. For insurers to keep up, they need to leverage targeted technologies to increase digital maturity across the entire customer relationship and value chain and provide their customers with a seamless, unique and tailored service experience. Tomorrow's insurers will have little in common with those of today. Six theses on how new technologies and the availability of enormous amounts of information will fundamentally change the world of insurers.

About eight years ago, the Single Resolution Mechanism entered into force and only shortly after, the Single Resolution Board (SRB) began its work in Brussels. Since then, many areas of resolvability planning have progressed well and banks are receiving ever more specific guidance and obligations. An overview of recent publications and current priorities.

The wider acceptance and active development of machine learning techniques and data analytics have made it possible to optimize and automate business processes. This presents a lucrative opportunity for banks to redesign their operations to cut processing times and improve transparency. We present the potential of these techniques by applying a machine learning approach to a hidden reserves/losses process that can often be found in the finance departments of banks.

In recent years the financial system’s regulators have worked towards discontinuing the existing reference rates for unsecured lending within the interbank market (IBOR, Interbank Offered Rate). Consequently, the important LIBOR (London Interbank Offered Rate) will most likely not be published anymore already by end of 2021.
That is why banks need to adapt their IT-systems towards a new interest-methodology to be able to offer lending being based on the new reference rates.

According to IFRS9, the prospective test is, with a few exceptions, to be used for assessing the effectiveness of hedge relationships. In the second of two parts, we present the implementation of the prospective test according to the Risk Induced Fair Value approach as well as its challenges in implementation.

The IASB regulations in the IFRS 9 Standard came into effect within the EU on 1 January 2018 with the aim to replace the previous approach of the IAS 39. In hedge accounting, the prospective effectiveness test becomes increasingly important in this new standard. Companies are also given the option of initially continuing to account for the effectiveness of hedge relationships in accordance with IAS39. The first part of the two-part article presents the effect of the regulatory requirements on the prospective test.
In the course of teh transition to ISO20022, the European payments infrastructure will change fundamentally and enormous opportunities in terms of process efficiency and an optimized customer experience will open up. Even though the integration of the standard is not mandatory from a regulatory perspective: To keep pace with international developments, extensive implementation projects lay ahead of European banks. In this article, we provide a brief overview of what is at stake and when the changes will take effect.
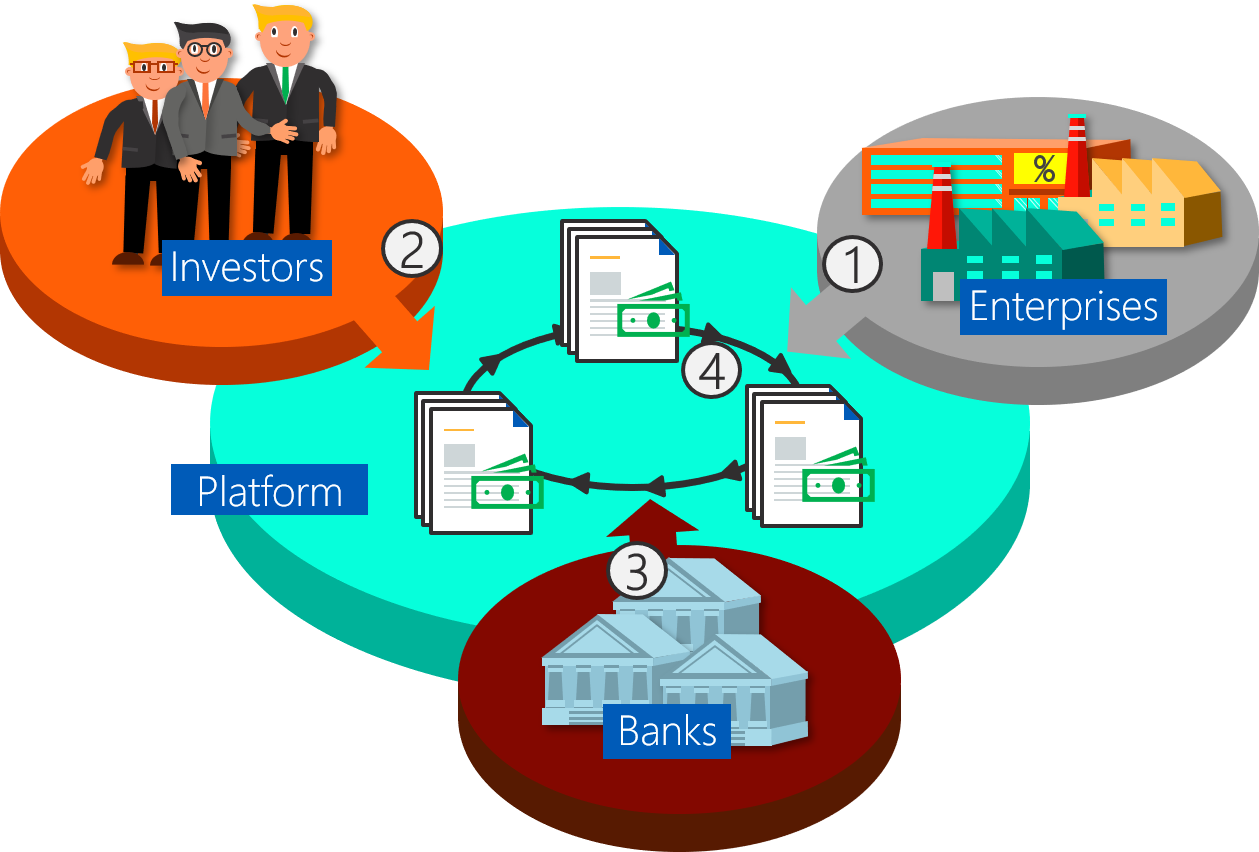
The Schuldschein market has seen an unseen spring of digital platforms, offering a digitized Schuldschein process, and supporting the boost of the Schuldschein in terms of transaction volume and deal numbers. The traditional process bears several inefficiencies that can easily tackled by shifting the process onto a digital platform. A platform can enhance standardization, transparency and processing time significantly. This article provides a current view on the platform evolution in the Schuldschein market.

From being a traditional niche product, the Schuldschein has evolved to being a serious alternative for other financing products: The traditional deed-based instrument, Germany-based and once owning a rather sedate and dusty reputation, now also attracts growing interest in international markets. With lower documentation requirements than a bond, higher transaction volumes than a loan, combined with a high level of standardization, the Schuldschein more and more stands out as a save and appealing way to invest and an uncomplicated way for companies to acquire external financing.

Managers of every level refer to the one or the other BI method to master the challenges of their daily work life and also the business departments employ BI techniques to get most out of their data. However, only few make use of the plethora of powerful self-service BI tools (SSBI tools) available on the market.
Thus, this article elaborates on the potential of BI in general and SSBI tools in particular. We summarize pros and cons and compare these to the well-known and very individual MS Excel & Access dashboard solutions.

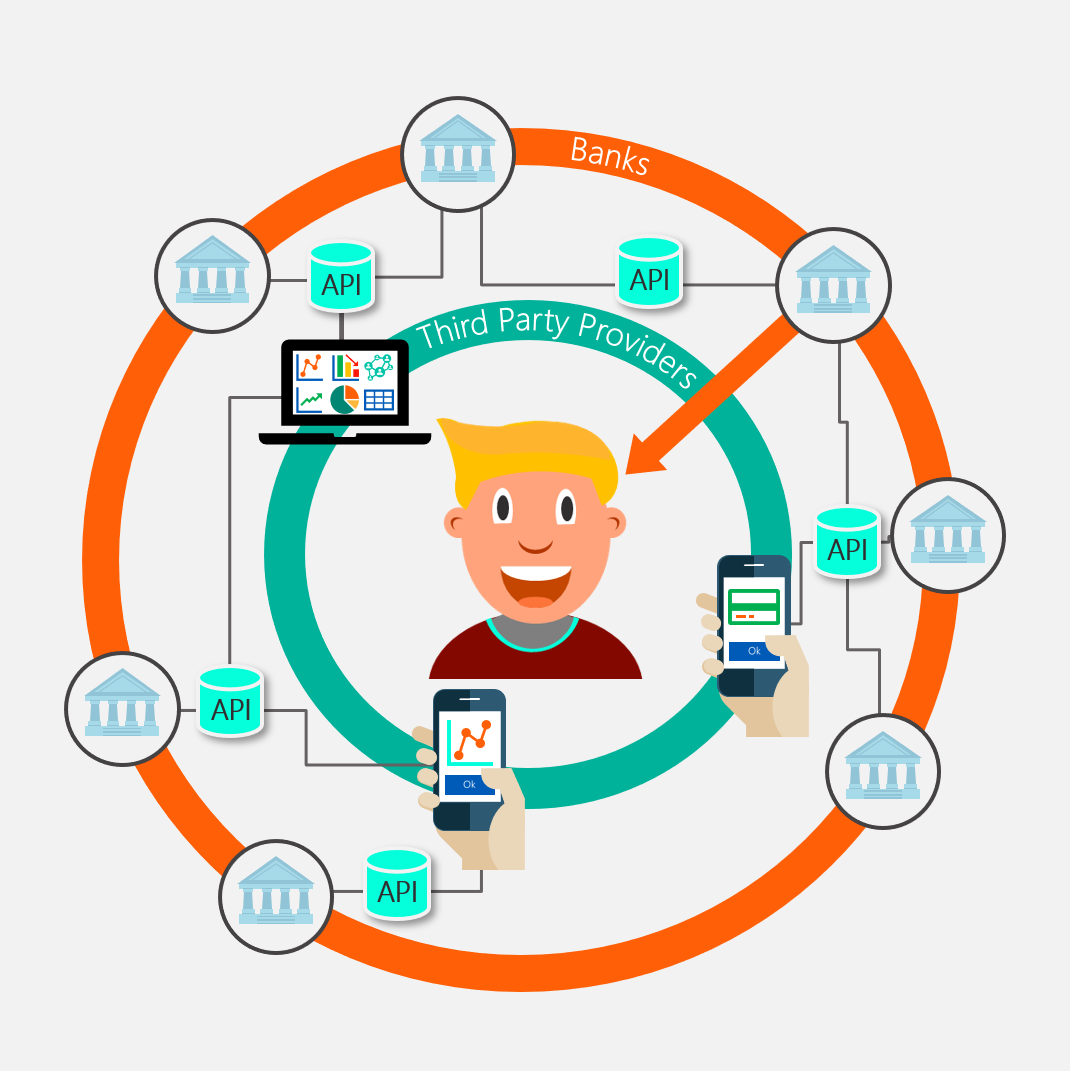
Open Banking or API Banking - the opening of the traditional banking sector to third-party companies – has become a major topic in finance. It’s not only the new Payment Services Directive (PSD2) of the EU, affecting all banks located in the EU, that leads to an energized, pioneering atmosphere. More and more IT-driven developments result in banks having to deal with the question of how to position themselves in a future market with not only plenty of new business opportunities, but also numerous new competitors on the rise. Open Banking is certainly strongly transforming the financial sector. It challenges the traditional structures and has the potential to revolutionize the entire industry.
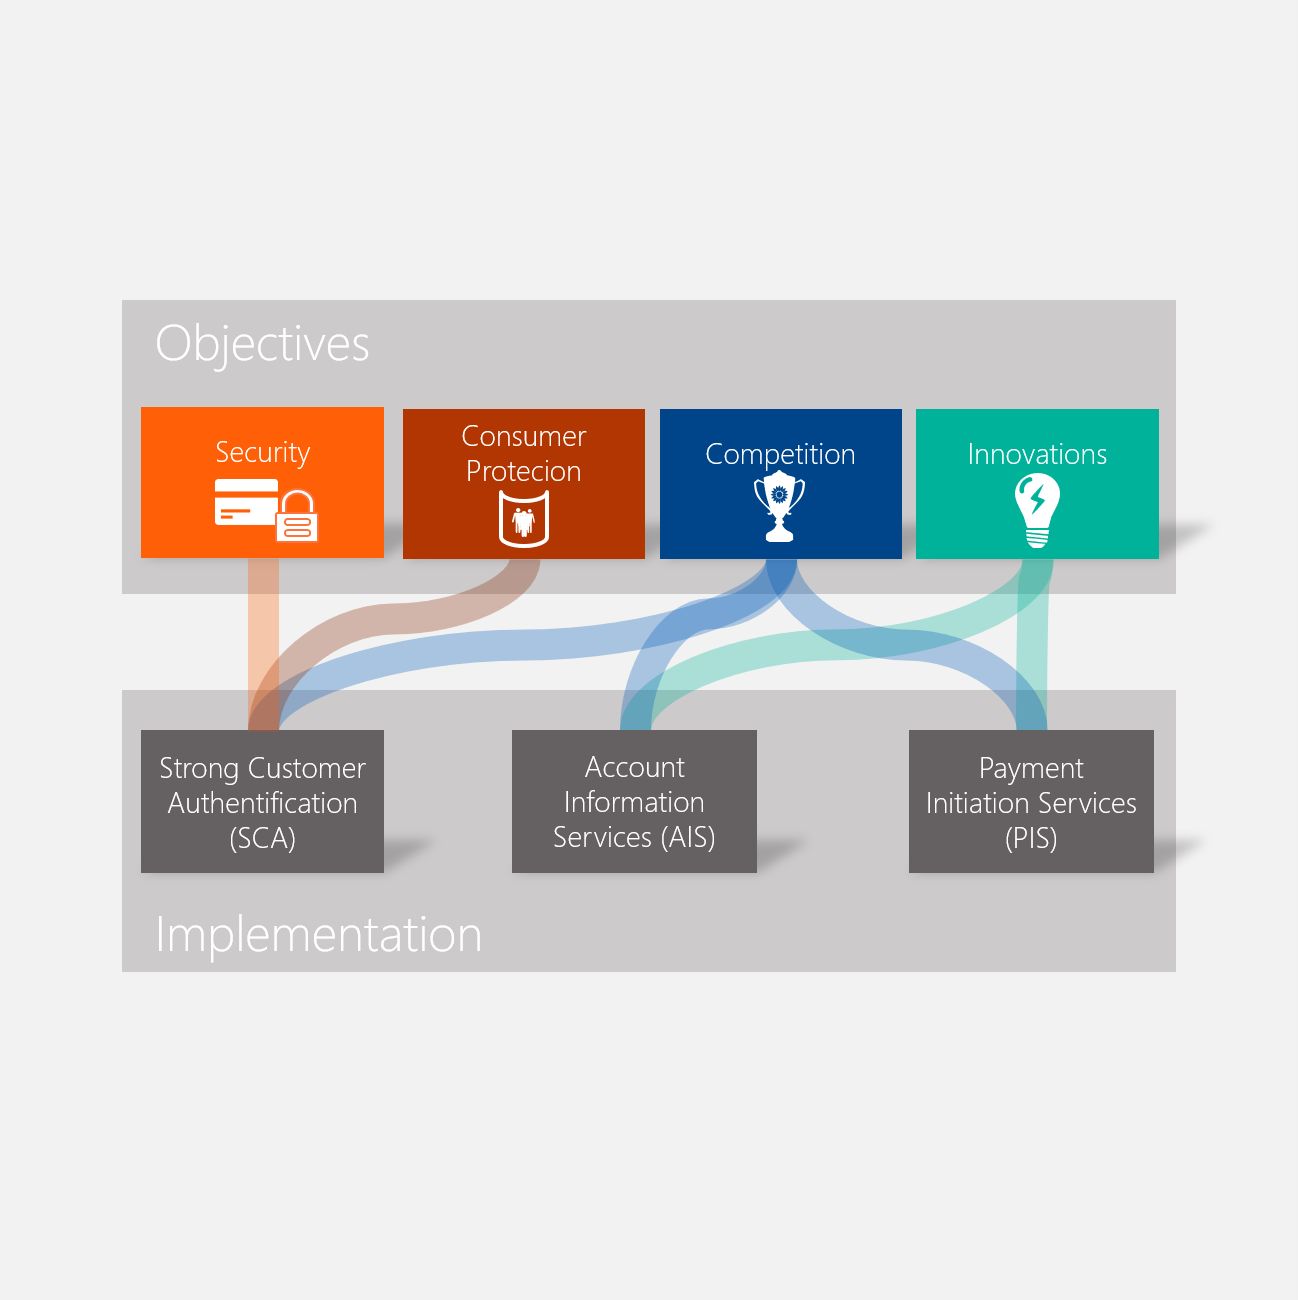
In financial industry, there’s hardly any topic that is being discussed more controversially than the PSD2, the "Payment Services Directive 2" of the EU. The directive entered into force on September 14, after a year and a half of preparation time. The new directive requires all banks in the EU to revise their security concepts and communication interfaces. This confronts institutions with the issue of an opening up of the industry to third-party providers and, in a broader context, the digitization and restructuring of the financial world.
PSD2 is the driving force of the concept of open banking in Europe and it is also shifting paradigms internationally.

In the world of established business processes, Robotic Process Automation (RPA), or short Robotics, is on everyone’s lips. As a tool to automate well-defined but time-consuming repetitive standard processes in a cost-effective way, RPA has versatile applications.

In 2017, the British Financial Conduct Authority (FCA) announced that the calculation of the LIBORs will not be continued after 2021. It is to be replaced with a new risk-free reference interest rate. All the main currencies will be affected. We describe the possible impacts as well as the necessary changes that are required during the conversion to the new interest rate.

In the context of the UK’s withdrawal from the European Union at the beginning of next year, many institutions decided to expand their business activities in Frankfurt or relocate there. Finbridge informs these institutions about the upcoming regulatory requirements.

In recent years, covenants have gained importance as a tool for credit risk management and have become established as a widespread creditor protection instrument in credit agreements.

An environment of recovering prime rates has led regulators to put more emphasis on interest rate risk in general and triggered the EBA release of an update to the corresponding EBA guidelines (EBA/GL/2018/02) on 19 July 2018 which is scheduled to enter into force as of 30 June 2019 and takes the standards formulated in BCBS 368 into account.